Your Thrift Savings Plan may end up being one of the largest assets you own. Yet many federal employees set their contribution percentage on day one and rarely look at it again. Good TSP retirement planning isn’t about chasing returns. It’s about a handful of well-timed decisions that compound over a career.
Here are seven moves worth reviewing this year, whether retirement is decades away or just around the corner.
1. Don’t Leave Free Money on the Table
FERS employees automatically get a 1% agency contribution. Your agency also matches your own contributions, dollar for dollar on the first 3% of pay and 50 cents on the dollar for the next 2%. Contribute 5%, and your agency adds a full 5%.
Illustrative example: On a $70,000 salary, a 5% contribution ($3,500) brings in $3,500 from your agency. If you contribute nothing, you receive only the automatic 1% ($700) and miss out on $2,800 a year in agency money.
2. Know Your 2026 Contribution Limits
The IRS raises contribution limits regularly, and 2026 brought meaningful increases:
- Standard limit: $24,500
- Age 50+ catch-up: an additional $8,000
- Ages 60–63 “super catch-up”: an additional $11,250
New for 2026: if your prior-year wages from TSP-eligible positions exceeded $150,000, your catch-up contributions must go into the Roth TSP. High earners should check their payroll elections to make sure catch-up dollars land in the right place.
3. Choose Traditional, Roth, or Both
The traditional TSP lowers your taxable income now. The Roth TSP uses after-tax dollars but can provide tax-free qualified withdrawals later. The right mix depends on where you expect your tax bracket to be in retirement compared to today.
Many federal employees use both to build tax diversification, which gives them flexibility over which bucket to draw from each year in retirement.
4. Match Your Fund Mix to Your Timeline
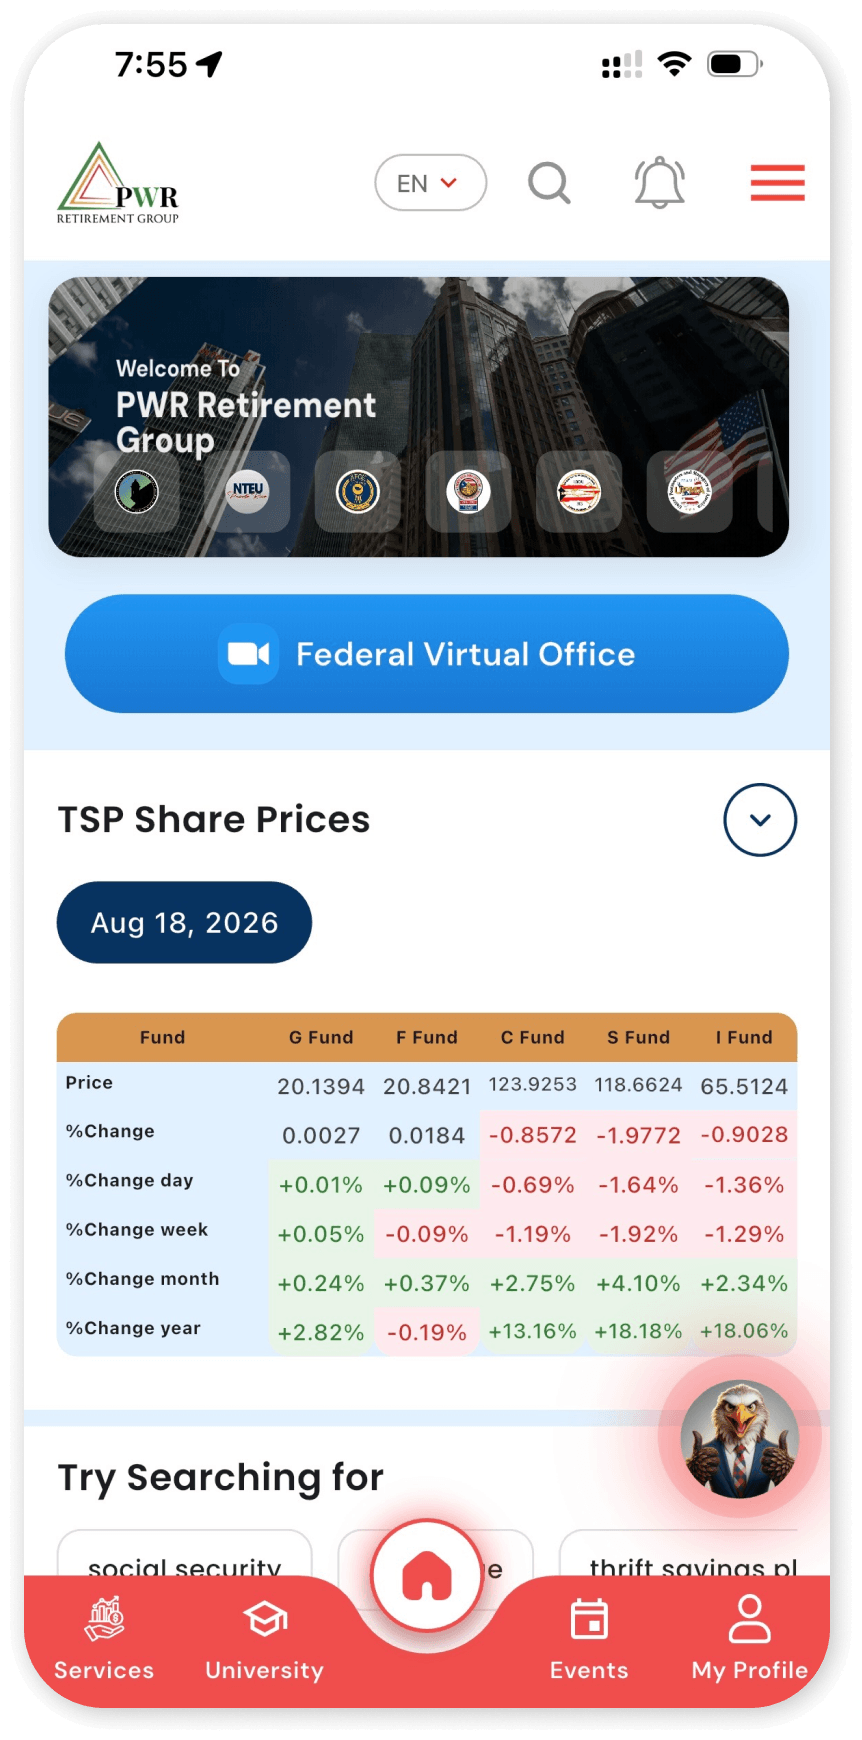
The TSP offers five core funds:
- G Fund: government securities
- F Fund: bonds
- C Fund: large U.S. companies
- S Fund: small and mid-sized U.S. companies
- I Fund: international stocks
The Lifecycle (L) Funds blend these five and become more conservative as your target date approaches. There’s no universally “best” fund. The right allocation reflects your time horizon, your comfort with market swings, and your other income sources, including your FERS annuity.
5. Plan Withdrawals Before You Retire
Building your balance is only half the job. How you take money out matters just as much. Your options include:
- Monthly, quarterly, or annual installment payments
- Partial withdrawals
- A TSP life annuity
- A combination of these
Timing matters too. Separating from service in or after the year you turn 55 (50 for certain public safety employees) generally lets you take withdrawals without the 10% early-withdrawal penalty. Required minimum distributions begin later in life, so it helps to coordinate them with your other income.
6. Weigh Rollover Options Carefully
When you leave federal service, you can keep your money in the TSP, roll it into an IRA, or do both. The TSP is known for its very low costs. An IRA may offer wider investment choices and more flexibility in how and when you take income.
Each path has tradeoffs in fees, control, and taxes. A rollover decision deserves careful review, not a quick signature.
7. Coordinate Your TSP With Your FERS Benefits
Your TSP doesn’t work in isolation. It sits alongside your FERS basic annuity, a possible FERS supplement, Social Security, and FEHB and FEGLI costs. Sound Federal Benefit Guidance looks at all of these together, so your TSP covers the gaps your pension doesn’t, in the most tax-efficient order possible.
A note for Puerto Rico participants: tax treatment of retirement income can differ from the mainland. Review your situation with a qualified tax professional before you set up withdrawals or rollovers.
Why TSP Retirement Guidance Makes a Difference
The TSP is straightforward to join and easy to put on autopilot. That’s exactly why small oversights, like a missed match, the wrong catch-up election, or a rushed withdrawal choice, can quietly add up over a career.
Personalized TSP Retirement Guidance helps you:
- Confirm you’re capturing the full agency match
- Align your fund allocation with your retirement timeline
- Build a withdrawal strategy that supports long-term income
- Compare TSP and IRA rollover options side by side
PWR Retirement Group works with federal employees, veterans, and retirees across the U.S. mainland and Puerto Rico to turn TSP balances into a clear, disciplined retirement income plan.
Frequently Asked Questions
1. How much should I contribute to my TSP to get the full agency match?
FERS employees who contribute at least 5% of basic pay receive the full agency contribution. That is the automatic 1% plus up to 4% in matching, for 5% total. Illustrative example: on a $70,000 salary, a $3,500 contribution brings in $3,500 from your agency. Contributing less than 5% leaves part of the match unclaimed.
2. What are the TSP contribution limits for 2026?
The standard 2026 limit is $24,500, combined across traditional and Roth TSP. Participants age 50 and older can add $8,000 in catch-up contributions, and those ages 60–63 can add $11,250 instead. If your prior-year wages from TSP-eligible positions exceeded $150,000, your catch-up contributions must go into the Roth TSP.
3. Should I choose the traditional TSP or the Roth TSP?
It depends on how your tax bracket today compares with what you expect in retirement. Traditional contributions lower your taxable income now. Qualified Roth withdrawals can be tax-free later. Many federal employees use both to build tax diversification, which gives them more flexibility over which account to draw from each year in retirement.
4. When can I withdraw from my TSP without the 10% early-withdrawal penalty?
If you separate from federal service in or after the year you turn 55, you can generally take withdrawals without the 10% penalty. For certain public safety employees, the age is 50. Ordinary income tax still applies to traditional balances. Puerto Rico participants should confirm how their retirement income is taxed with a qualified tax professional before setting up withdrawals.
5. Should I keep my money in the TSP or roll it over to an IRA when I retire?
There’s no single right answer. The TSP is known for its very low costs. An IRA may offer wider investment choices and more flexibility in how and when you take income. You can also keep part of your balance in each. Compare fees, control, and tax treatment side by side before you sign any rollover paperwork.
Disclaimer: The information provided on this website and mobile application is for general educational and informational purposes only and does not constitute financial, investment, tax, legal, or retirement advice. PWR Retirement Group is an independent organization and is not affiliated with, endorsed by, or acting on behalf of any labor union, government agency, or employer. Users should consult an appropriately licensed financial professional, tax professional, or attorney regarding their individual circumstances before making financial, tax, legal, or retirement-related decisions.
PWR Retirement Group is an independent financial education firm and is not affiliated with, endorsed by, or sponsored by any federal agency, federal organization, government entity, or union.